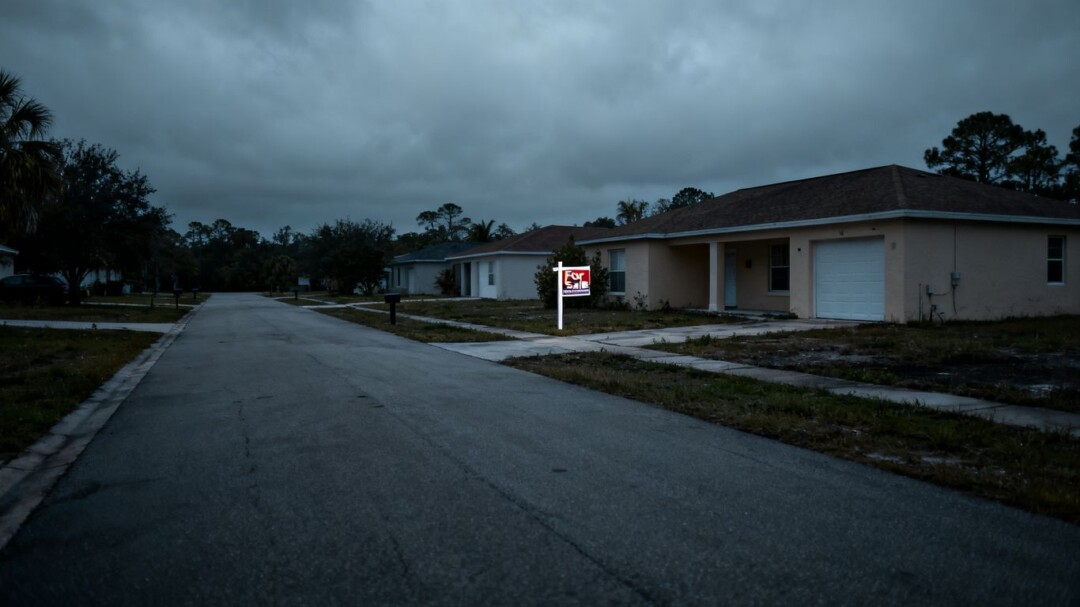
Florida homeowners are facing longer waits and tougher negotiations as housing inventory grows and buyers become more cautious. A new state ranking places Florida last for sellers, while Tampa-area data show homes outnumber prospective buyers. Mortgage rates have also climbed, adding another obstacle for people trying to make a sale.
Key takeaways
Florida’s combination of high inventory, longer selling times and fewer above-asking offers is shifting leverage toward buyers. Higher mortgage rates may further limit what some buyers can afford.
- Florida ranked as the hardest state to sell a home in a study of 48 states.
- The state had 206,508 homes listed, with a typical home taking 73 days to sell.
- A 30-year mortgage rate reached 7.28% on Oct. 1, according to WFLA.
- Tampa had 86% more homes for sale than interested buyers, Redfin reported.
Inventory and slower sales weigh on Florida sellers
The Underwood Law Firm ranking drew on seven Redfin Data Center measures, including active listings, days on market, price cuts and the share of homes sold above asking. Florida led the study in active inventory and recorded just 10.9% of homes selling for more than the listed price—signs that buyers have more options and sellers less negotiating power.
Texas, South Carolina, Montana and Arizona rounded out the five most difficult states for sellers. At the other end of the ranking, Connecticut was the easiest market, with 55.8% of homes selling above asking.
Tampa sellers are cutting prices and offering concessions
In Tampa, Redfin found there were 86% more homes available than people looking to buy. The report also put the share of listings with price reductions at 23%, placing the city among the top 10 nationally for that measure.
Tampa realtor Julie Lawrence told WFLA that some sellers still expect prices comparable to what they paid in 2021, though those expectations may not fit current conditions. She said many are reducing prices after a few weeks and offering help with closing costs—concessions that were less common during the pandemic-era market.
Higher borrowing costs add pressure
WFLA reported that the 30-year mortgage rate rose to 7.28% on Oct. 1, up a quarter of a percentage point over the prior week. Higher rates increase the cost of financing a purchase, potentially narrowing the pool of buyers able or willing to make an offer.
For sellers, the combination of costly borrowing and abundant listings can mean adjusting the asking price, waiting longer or negotiating on terms. The figures point to a more buyer-friendly market, though conditions can differ by neighborhood and property type.