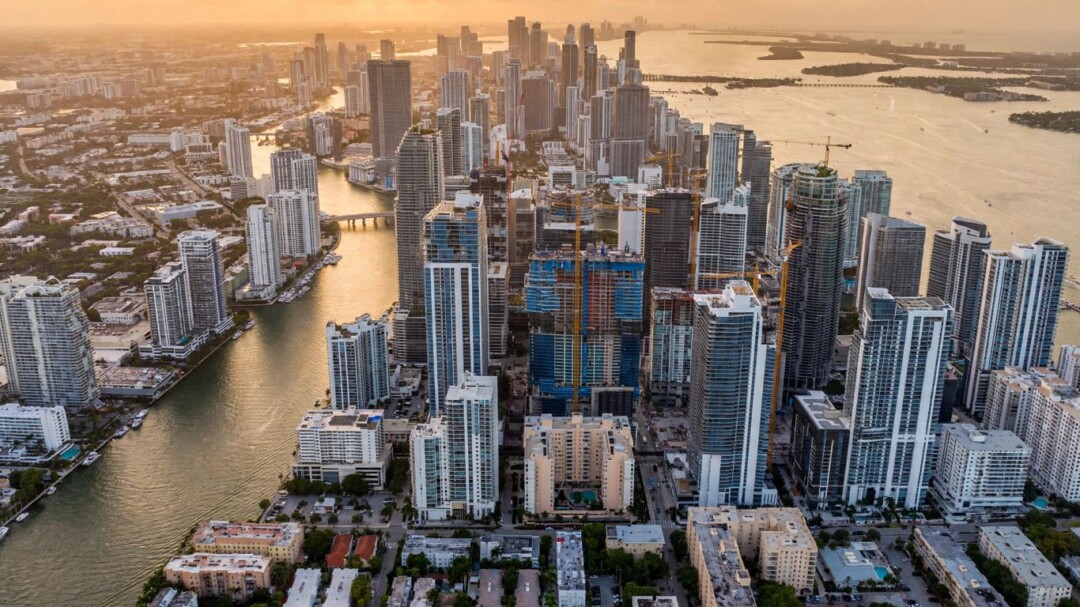
Brickell’s condo market could face a sharp test as thousands of new units are expected to arrive by 2028. A David Siddons Group analysis warns that investor-focused, lower-priced buildings may face the greatest competition, while established luxury and new high-end towers could be more resilient. The forecast points to a divided market, not a neighborhood-wide downturn.
Key takeaways
The report’s central concern is that new supply may intensify pressure on buildings already competing for buyers and renters. Its estimates are projections, and outcomes will depend on deliveries, demand and conditions in each building.
- The analysis cites about 1,560 Brickell condos for sale and roughly 18 months of resale inventory in September 2026.
- Nearly 4,000 new units are in the pipeline; the report estimates about 825 could return to resale around 2028.
- It identifies Icon Brickell, Jade, Aston Martin Residences, 1010 Brickell, Reach and SLS Lux as especially exposed.
- The report sees established waterfront properties and new ultra-luxury towers as comparatively better positioned.
Why the report sees a 2028 supply squeeze
The forecast centers on competition between incoming mid-market units and existing investor-oriented condos. The group estimates that roughly one-quarter of new units may be resold, potentially adding about 825 listings to approximately 750 newer condos already for sale. Most of the remaining units could enter the rental market, adding competition for landlords as well.
The report compares the coming wave with a 2015 correction, when it says roughly 2,200 to 2,300 new units contributed to rising inventory. This time, the pipeline is larger, though the impact will depend on whether buyer and renter demand grows alongside supply.
Buildings the analysis flags
The six named buildings share characteristics the report considers vulnerable: significant investor ownership, relatively compact layouts and competition from newer projects. It also points to potential view obstruction and building-specific concerns as factors that may influence resale appeal.
The analysis highlights additional pressures at some properties. It says Jade has about 20 months of inventory and faces nearby construction, while Icon Brickell has experienced amenity disruptions and building work. Aston Martin Residences, it adds, has already seen price reductions and still has units to sell. These conditions do not establish that every unit will lose value; floor plan, view, condition and asking price matter.
A market split by price and buyer
The report distinguishes investor-grade condos, generally below $1 million, from established luxury and newer ultra-luxury homes. The lower-priced segment is most directly exposed to competing listings and rental supply. The analysis says Four Seasons, Santa Maria and Bristol Tower benefit from established owner communities and service, with reported sales around $1,000 to $1,400 per square foot.
At the top end, Mandarin Oriental and St. Regis are reported about 85% sold, while 1428 Brickell is about 70% sold. The group attributes demand for larger, service-oriented residences to corporate relocations and wealth migration, including firms establishing a presence in Brickell. Those sales figures and market explanations reflect the report’s assessment, not a guarantee of future performance.
What buyers and owners should watch
For owners in investor-heavy buildings, the analysis argues that selling before major deliveries could mean facing fewer competing listings. Buyers, meanwhile, can assess whether a specific condo’s price reflects its building condition, rental competition, view and likely future supply. The report’s broader message is that Brickell should not be treated as a single market: building-level details and buyer demand may produce very different outcomes.